Request a Diagnostic Conversation

Retail

When Revenue Growth Hides Margin Deterioration

Revenue is up and gross margin looks stable. On paper, the quarter reads well.

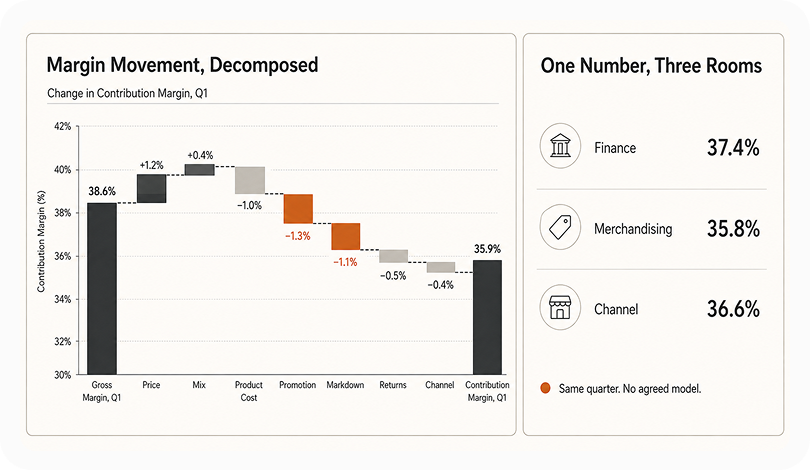
Then the board asks what actually changed in the underlying economics, and finance, merchandising, and channel teams produce three different explanations. Contribution margin, once promotions, markdowns, returns, and

channel-specific costs are considered under an agreed contribution model, may already be moving in the wrong direction, but without that agreed model, nobody can say for certain, or since when.

Signal 1

A stable headline, an uncertain core

Gross margin percentage barely moves, while leadership increasingly suspects contribution economics are deteriorating beneath it, with no agreed way to confirm it

Signal 2

Three numbers, one meeting

Finance, merchandising, and channel teams each bring a different margin figure to the same review

Signal 3

Cost hiding past the discount

A promotion clearly drove volume, but its full cost, once markdowns and returns are counted, was never calculated

Signal 4

A quarter-end surprise

Markdown and write-off figures arrive as a shock rather than a tracked, expected trend

Leadership Question

When margin moves, can we say how much came from price, mix, cost, promotion, or channel, or only that it moved?

What's Actually Breaking

Contribution Has No Agreed Definition

The organisation reports gross margin consistently, but lacks an agreed view of contribution once channel-specific costs, promotions, markdowns, and returns are included. Different teams fill that gap differently.

Promotional Cost Hides Past the Headline Discount

A promotion's listed discount is only part of its real cost. Markdowns on unsold stock, returns, and potential cannibalisation of full-price demand rarely get attributed back to the promotion that caused them.

Markdown Decisions Get Made Without Seeing the Impact

Buying and merchandising decide to mark down stock based on sell-through, without an estimated view of the margin consequence until finance closes the books, weeks later.

Request a Diagnostic Conversation

Why the obvious fix falls short

A Bigger Finance Dashboard

Adds more views of the same undecomposed number. Doesn't reveal whether last quarter's dip was price, mix, promotion, or markdown.

Request a Diagnostic Conversation

Cutting Promotional Spend Across the Board

Performance often varies materially between promotions, and blanket cuts may remove activity that is still commercially effective.

Decompose the Movement

Break each quarter's margin shift across price, volume and mix, product cost, promotion, markdown, returns, and channel economics, using agreed rules rather than ad hoc judgment.

Flag Where Attribution Relies on Assumption

Where a rule depends on an assumption rather than observed data, that assumption is flagged explicitly, not presented as fact.

Assign Accountability Before the Next Cycle

Ownership for improving the weakest inputs is clarified before the next quarter's close.